The wrong lender first
Lenders assess differently. Use the generous one too early and you’ve burned the capacity you’ll need later.
Finance StrategyResidential & Commercial
The difference isn’t income. It’s structure. I’m Tanya, a former accountant who finances residential and commercial portfolios engineered to scale.
Explore the strategy30 minutes. No obligation.
You leave with your next move.
Your bank won’t show you where it is. It’ll just say no, usually right before the deal you actually wanted.
Lenders assess differently. Use the generous one too early and you’ve burned the capacity you’ll need later.
Cross-securing hands one bank control of your whole portfolio, and your exit options with it.
Loan splits and ownership set up casually can cost you deductions for years. This is where an accountant’s eye pays.
I design your finance so you
never meet the ceiling.
Two markets. One strategist.
Equity release, lender sequencing and loan structure planned across the whole portfolio, so each purchase unlocks the next instead of blocking it.
Commercial credit reads your business, your trust and your tax position, not just a valuation. I speak that language natively, because I used to prepare it.
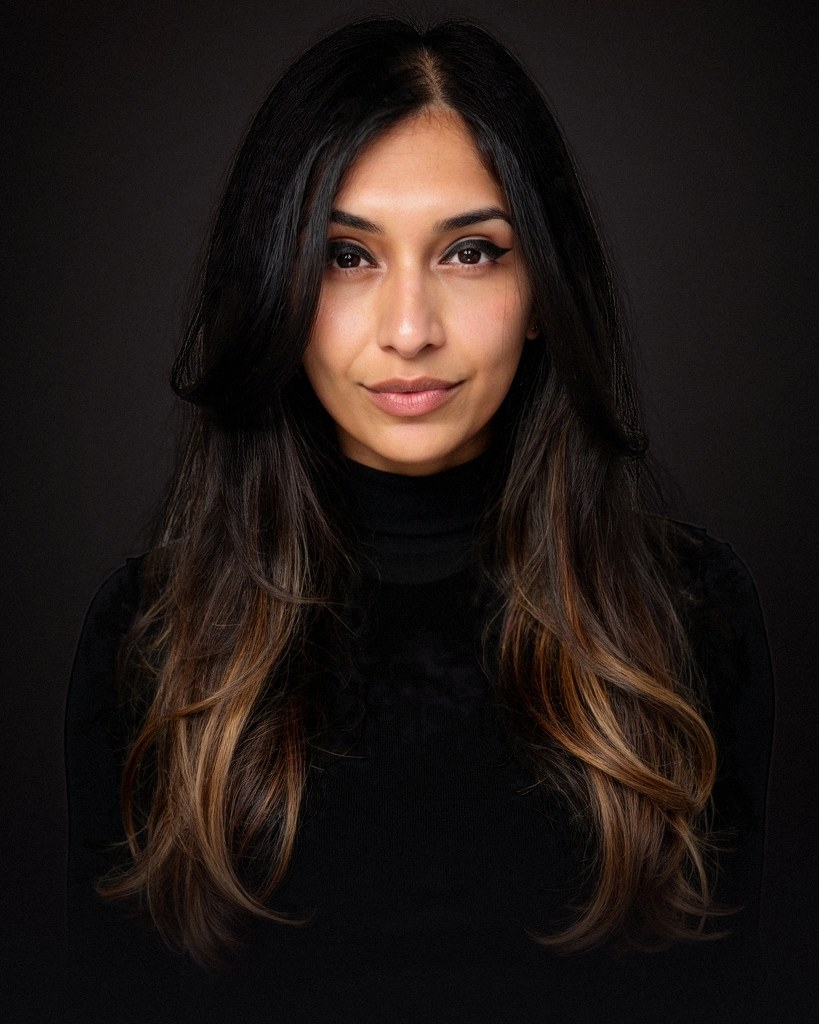
Accountant first. Broker second. Strategist always.
Because how you earn, hold and structure your wealth decides what a lender will give you next. I spent years as an accountant on the other side of the numbers, and later completed a PhD in finance and AI. Now I use both to build lending positions banks say yes to, quickly, and on your terms.
You bring the ambition. I bring the spreadsheet, and I make the whole thing fun.
The ascent
Thirty minutes on where you are, where you want the portfolio to be, and what’s quietly in the way.
Capacity, cash flow and structure modelled across 50+ lenders, with the order to use them in.
Accountants, solicitors, buyers agents, deadlines and paperwork handled through to settlement. You stay focused on the deal.
Ongoing reviews, rate negotiation after every move, and a plan already waiting for your next purchase.
Investor story
Liam came to me with one home, a strong income and a lender that had already capped him out. We re-sequenced the lenders, released the equity sitting idle in the family home and split the structure so every purchase stood on its own two feet.
Residential first, for growth. Then a commercial asset, for the yield that carried the next round. Today Liam holds a $7M portfolio, and the bank that said no is still on the panel. Just further down the list.
Find out what your limit really is“This is the second property Tanya has helped me purchase, and I can’t recommend her enough.”
“That’s Tanya. The best mortgage broker, hands down, who brings a calming presence.”
“Dealing with Tanya has been an absolutely brilliant experience.”
Your bank can only offer its own products, and it isn’t bound to act in your best interest. I compare 50+ lenders and I am legally bound by Best Interest Duty. If your bank is genuinely the right fit, I’ll tell you.
Especially you. The cheapest time to get structure right is before the second purchase, not after the fourth.
Not necessarily. Depending on your position it can be as little as 5%, and existing equity can often replace cash entirely. The private review shows you exactly where you stand.
Both, and that’s the advantage. One strategist sees how your homes, investments, business and SMSF affect each other, instead of three brokers working blind.
Every loan settled through CitrineX helps fund donations to the Little Hearts Foundation, supporting children in need across Australia and the Pacific Islands.
Meet Little HeartsBy appointment
Tell me where you want the portfolio to be. I’ll come back with how to get there, and which lender takes you there first.
+61 424 455 765Melbourne · Advising investors Australia-wide